Understanding why SIP is the best way to invest in mutual funds is key to building sustainable long-term wealth without timing the market. India crossed 10 crore active SIP accounts in 2026. That is not a trend. That is a shift in how ordinary Indians build wealth.
But most people still park their savings in fixed deposits or recurring deposits, earning returns that barely keep up with inflation. If your money grows at 6% and prices rise at 5%, you are making a 1% real return. That is not investing. That is treading water.
SIP (Systematic Investment Plan) changes this. Here is why, with actual numbers.
What is SIP in Simple Terms?
SIP lets you invest a fixed amount every month into a mutual fund. Think of it like a recurring deposit, except your money goes into the stock market through a professionally managed fund instead of sitting in a bank.
You pick the amount (starting from ₹500), pick the date, set up auto-debit, and the money gets invested automatically every month. No paperwork each time. No need to watch the market.
7 Reasons SIP is the Smartest Way to Invest
1. You Do Not Need a Large Amount to Start
A bank fixed deposit often needs ₹10,000 or more. A SIP starts at ₹500 per month.
If you earn ₹20,000 a month and save even ₹2,000 through SIP, you are investing ₹24,000 a year. Over 15 years at 12% average annual returns, that ₹2,000/month becomes approximately ₹10.1 lakh from a total investment of ₹3.6 lakh.
That math does not work with a savings account at 3-4%.
2. Rupee Cost Averaging Removes the Guessing Game
The biggest fear new investors have: “What if the market crashes after I invest?”
With SIP, a crash actually helps you. Here is how:
Total invested: ₹20,000. Total units: 478.9. Average cost per unit: ₹41.76
If you had invested ₹20,000 as lumpsum in January, you would have 400 units at ₹50 each. The SIP investor got 478.9 units for the same money because the dips brought down the average cost.
This is rupee cost averaging. It turns market volatility from an enemy into an advantage.
3. Compounding Works Harder Over Time
Compounding means your returns earn their own returns. The longer you stay invested, the more dramatic the effect.
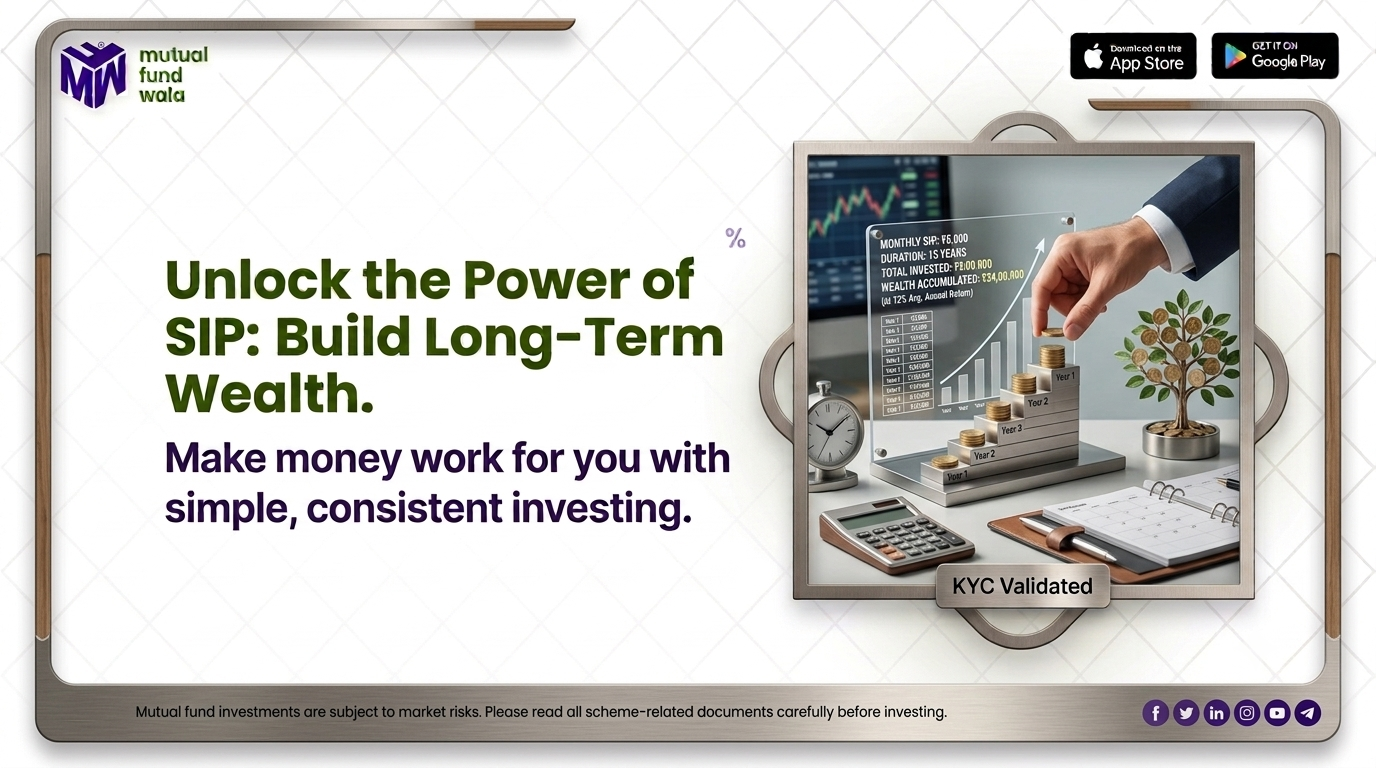
Here is what a ₹5,000/month SIP looks like at 12% average annual returns (you can run your own numbers using our SIP calculator):
4. It Builds a Savings Habit Automatically
Most people do not fail at investing because they chose the wrong fund. They fail because they never invest consistently.
SIP solves this by removing the decision from your hands. Set up auto-debit once, and the money moves before you can spend it. Over months, you stop noticing the deduction. Over years, you notice the corpus.
5. You Can Pause, Increase, or Stop Anytime
Unlike a 5-year FD where early withdrawal costs you a penalty, SIP has no lock-in (except ELSS funds which have a 3-year lock-in for tax saving).
- Got a salary hike? Increase your SIP or start a second one.
- Tight month? Skip one instalment. No penalty.
- Need the money? Redeem your units (after any applicable exit load period, usually 1 year for equity funds).
6. SIP Works Even If You Know Nothing About the Stock Market
You do not pick stocks. A professional fund manager does that. Your job is to pick a fund category (large cap, flexi cap, index fund), decide an amount, and stay invested.
This makes SIP suitable for anyone with a bank account and a PAN card: teachers, shopkeepers, IT employees, government workers, freelancers. You do not need a finance degree.
7. Tax Benefits Through ELSS SIP
If you invest in an Equity Linked Savings Scheme (ELSS) through SIP, you can claim deduction up to ₹1.5 lakh under Section 80C of the Income Tax Act. ELSS has the shortest lock-in period (3 years) among all 80C options.
So your SIP can save tax and build wealth at the same time.
SIP vs FD vs RD vs PPF: The Real Comparison
The key insight: FD and RD returns are fully taxable. If you are in the 20% tax bracket, your 7% FD effectively gives you 5.6% after tax. With inflation at 5-6%, your real return is nearly zero.
SIP in equity mutual funds carries market risk, but over 10+ year periods, equity has historically delivered significantly higher inflation-adjusted returns than any fixed-income product.
The bottom line: FD and RD protect your money. SIP grows it. The right approach is to keep 6 months of expenses in FD/savings for emergencies, and invest the rest through SIP.
What Happens to Your SIP During a Market Crash?
This is the question every new investor asks. Let us look at what actually happened.
March 2020 (COVID crash): The Nifty 50 fell from 12,000 to 7,500 in one month. Investors who panicked and stopped their SIPs locked in losses. Investors who continued their SIPs bought units at the lowest prices in years.
By December 2020, Nifty was back above 13,000. Those who kept their SIPs running during the crash had accumulated cheap units that were now worth significantly more.
The lesson: Market crashes are the best thing that can happen to a running SIP. You are buying the same mutual fund at a discount. Stopping SIP during a crash is like walking out of a sale because the prices dropped.
5 SIP Mistakes That Cost You Money
1. Stopping SIP when markets fall This is the most common and most costly mistake. A falling market means cheaper units. Your SIP is designed to take advantage of exactly this.
2. Expecting guaranteed returns SIP is a method of investing, not a guarantee. Returns depend on market performance. Over 10-15 years, equity mutual funds have historically delivered strong returns, but short-term results can be negative.
3. Starting multiple SIPs without a goal Running five SIPs of ₹1,000 each across random funds creates overlap and confusion. Better to run two or three focused SIPs aligned to specific goals (retirement, child’s education, house down payment).
4. Ignoring step-up SIP If you started a ₹3,000 SIP three years ago and your salary has grown 30% since, your SIP should grow too. A 10% annual increase in SIP amount can nearly double your final corpus compared to a flat SIP.
Example at 12% returns over 20 years:
- Flat SIP of ₹5,000/month: ~₹49.9 lakh
- Step-up SIP of ₹5,000/month (increased 10% every year): ~₹95+ lakh
5. Choosing the wrong fund category for your time horizon Equity SIP works best for goals 7+ years away. For goals 3-5 years away, consider hybrid or balanced advantage funds. For goals under 3 years, debt funds or liquid funds are more appropriate.
How to Start Your First SIP
- Get your KYC done. You need PAN card, Aadhaar, and a bank account. KYC can be completed online in minutes through most platforms.
- Decide your monthly amount. A good starting point: 20% of your take-home salary. Even ₹500 is fine if that is what you can commit to consistently.
- Pick a fund category. For beginners with a 10+ year horizon, a Nifty 50 index fund or a flexi-cap fund is a solid starting point. Keep it simple.
- Set up auto-debit. Link your bank account and choose a date. Many investors pick the 5th or 10th so the SIP runs soon after salary credit.
- Do not check it every day. Review once every 6 months. The whole point of SIP is that it works in the background while you focus on your life.
If you are in Delhi and want hands-on help starting your first SIP, our SIP investment in Delhi team can guide you through the entire process.
 Shashi Kant Bahl