 Shashi Kant Bahl
SWP Calculator
(Systematic Withdrawal Plan)
An SWP Calculator is an online tool that estimates how regular withdrawals can affect your mutual fund corpus over time. By entering your initial investment, monthly withdrawal, expected return and investment period, you can estimate your potential withdrawals and the corpus remaining after each period. An SWP calculator can help you compare different withdrawal scenarios and understand how changes in withdrawal amounts or expected returns may affect the longevity of your investment.
AMFI Registered • Est. 2005
Inflation-Adjusted Projections
Built for Retirement & Income Planning
SWP Calculator
Plan regular income from your investments.
Your SWP Estimate
Invested vs. total withdrawn
Calculate Systematic Withdrawals From Mutual Funds
Building wealth is only one part of investing. The next step is understanding how your accumulated corpus can support regular withdrawals. An SWP Calculator helps estimate monthly withdrawals, investment duration, expected returns, and the potential value of the remaining corpus.
For investors approaching retirement or looking for a regular income from mutual fund investments, an SWP calculator offers a simple way to see how different withdrawal amounts and time periods may affect the invested corpus.
What This SWP Calculator Does
This systematic withdrawal plan calculator shows how long your investment may last and how much regular income you can withdraw from it. It considers:
- Your initial investment amount
- Your monthly withdrawal amount
- The expected rate of return
- An optional yearly increase in withdrawals to keep pace with inflation
The results show how your balance changes over time and how much corpus may remain at the end of the period.
How to Use the SWP Calculator
- Enter the total amount you plan to invest initially.
- Set the monthly amount you wish to withdraw.
- Choose an expected return based on your investment strategy.
- Select the withdrawal period to match your income needs.
The calculator then shows how your balance reduces over time, so you can pick a withdrawal amount that your corpus is more likely to sustain.
When This SWP Calculator Is Useful
- When you want a predictable monthly income after retirement.
- When you want to plan withdrawals for a fixed period like 10, 15, or 25 years.
- When you want to check if your current corpus can support a desired withdrawal amount.
- When you want to compare different withdrawal amounts before starting an SWP.
This SWP calculator provides estimates based on your inputs. Mutual fund returns are market-linked and not guaranteed. Actual results may vary due to market movements, taxes, and the timing of withdrawals. Review your plan regularly and consult a qualified professional before making decisions.
What Is SWP in Mutual Funds and How Does It Work?
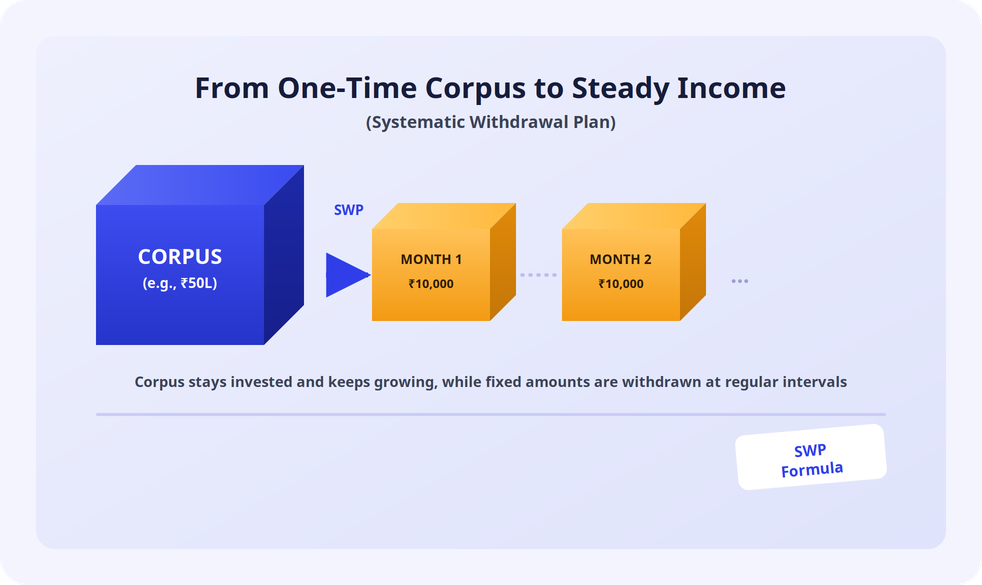
SWP stands for Systematic Withdrawal Plan. It lets you withdraw a fixed amount from your mutual fund investment at regular intervals. Each withdrawal redeems units equal to that amount, while your remaining units stay invested. You can usually choose a monthly, quarterly, half-yearly, or yearly frequency, depending on the scheme.
How it works:
Corpus → Withdrawal instruction → Units redeemed → Remaining corpus stays invested
- Corpus: You start with a lump sum invested in a mutual fund scheme.
- Withdrawal instruction: You set a fixed amount and frequency (monthly, quarterly, etc.) for your SWP.
- Units redeemed: On each withdrawal date, units equal to that amount are redeemed at the day’s NAV.
- Remaining corpus stays invested: The rest of your units continue in the market, still earning returns between withdrawals.
SWP Calculator and How It Helps
An SWP calculator helps you estimate how long your corpus may last based on your withdrawal amount, expected returns, and time horizon. The aim is to balance what you take out with what your remaining investment may earn.
It also shows how your remaining corpus changes over time, which helps you spot a withdrawal rate that could exhaust your money too early.
SWP Calculator With Inflation Gives Real Clarity
An SWP can convert an invested corpus into a structured stream of regular withdrawals.
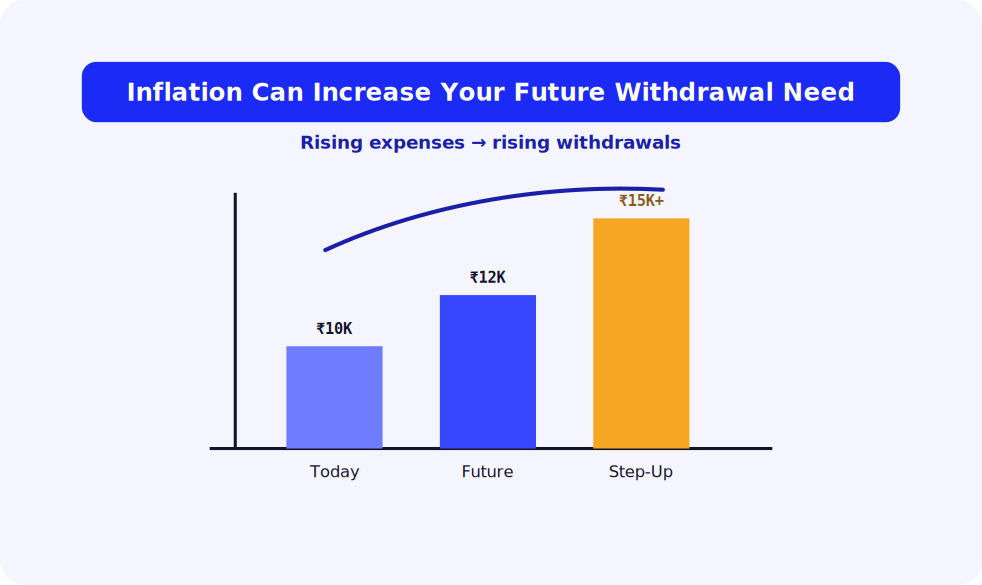
One of the most important variables in withdrawals is inflation.
An SWP calculator with inflation raises your withdrawal each year to account for rising costs. This helps your withdrawals keep pace with rising expenses over time.
Without this adjustment, what seems sufficient today may fall short in the future.
This is why tools like the SWP calculator India or the systematic withdrawal plan calculator India often include inflation assumptions for better planning.
SWP Investment Plan and Strategy
A good SWP plan is about sustainability, not just withdrawals. If your withdrawal rate is close to or below the return your investment earns, your corpus is more likely to last. If it is well above, the corpus shrinks faster, especially when markets fall.
Try a few withdrawal amounts in the calculator to find a number that balances your income needs with how long you need the money to last. This matters most for retirees who depend on their investments for regular income.
SWP vs SIP and Transition Planning
SIP and SWP serve different stages of your financial journey. SIP helps you build wealth through regular investing. SWP helps you draw a regular income from that wealth.
Many investors move from one to the other as they near retirement: they stop their SIPs and start withdrawals from the corpus they have built. You can estimate the accumulation phase with our SIP calculator and then use this SWP calculator to plan the withdrawal phase.
Some tools, like a SIP withdrawal calculator, can help simulate this transition.
Practical Questions Around SWP Calculator India
- Can I start an SWP immediately after investing?
- What is the minimum amount for an SWP?
- How to invest in a SWP usually involves selecting a mutual fund and setting up a withdrawal instruction.
Returns and Expectations From SWP
Another common question is what is the rate of return in SWP.
The return is not fixed. It depends on the performance of the underlying mutual fund. Equity funds may offer higher returns but greater volatility, while debt funds offer greater stability but lower returns.
This is why the choice of fund matters. The fund category should match your risk comfort and income needs.
Is SWP a Good Option?
For many investors, especially retirees, whether SWP is a good option comes down to the need for consistent income.
SWP provides regular cash flow while keeping the remaining corpus invested. This balance makes it suitable for long-term income planning.
However, withdrawal rates must be planned carefully to avoid exhausting the corpus too early.
Final Thought
SIPs bring discipline to building wealth. SWPs bring structure to using it. Before you start withdrawals, use this SWP calculator to test a few scenarios, such as a higher or lower monthly amount, a different return, or a longer period, and see how long your corpus may last. If you’d like help setting up an SWP, the MutualFundWala team is here to support you.
Popular Calculators
How to use the SWP Calculator
Four inputs help you estimate regular withdrawals and the remaining corpus.

Enter the total investment
The lump sum you'll withdraw from.

Set the monthly withdrawal
The regular income you want to receive.

Add the expected return
The annual return assumption for your investment.

Select the time period
How long you want the withdrawals to continue.
FAQs – SWP (Systematic Withdrawal Plan)
How often can I receive SWP withdrawals?
SWP withdrawals can generally be scheduled at regular intervals such as monthly, quarterly, half-yearly, or yearly, depending on the options available for the mutual fund.
Does SWP reduce the number of mutual fund units I hold?
Yes. Each SWP withdrawal involves redeeming a certain number of mutual fund units based on the applicable NAV. Your remaining units stay invested.
What happens to my SWP if the mutual fund value falls?
If the fund’s value falls, more units may need to be redeemed to meet the same withdrawal amount. This can reduce the remaining corpus faster, depending on market performance and withdrawal levels.
Can I change my SWP withdrawal amount later?
Yes, an SWP can generally be modified, subject to the mutual fund’s applicable rules and procedures. You may be able to change the withdrawal amount or other instructions.
Can I stop an SWP whenever I want?
An SWP can generally be stopped by submitting a cancellation request, subject to the mutual fund’s applicable process and cut-off requirements.
Are SWP withdrawals taxable?
SWP withdrawals can have tax implications because each withdrawal involves redemption of mutual fund units. The applicable tax treatment depends on factors such as the fund type, holding period, and prevailing tax rules.
Ready to Create a Regular Monthly Income?
Start your Systematic Withdrawal Plan today for steady, structured monthly cash flows from your mutual fund investments.
Get SWP Support From Our Team
A withdrawal projection is a starting point — our team can help you understand how SWP works and support you in setting one up.
- Support from our team via call, WhatsApp, or email
- Help understanding SWP and how it works
- No pressure - just clarity on your options