 Gaurav
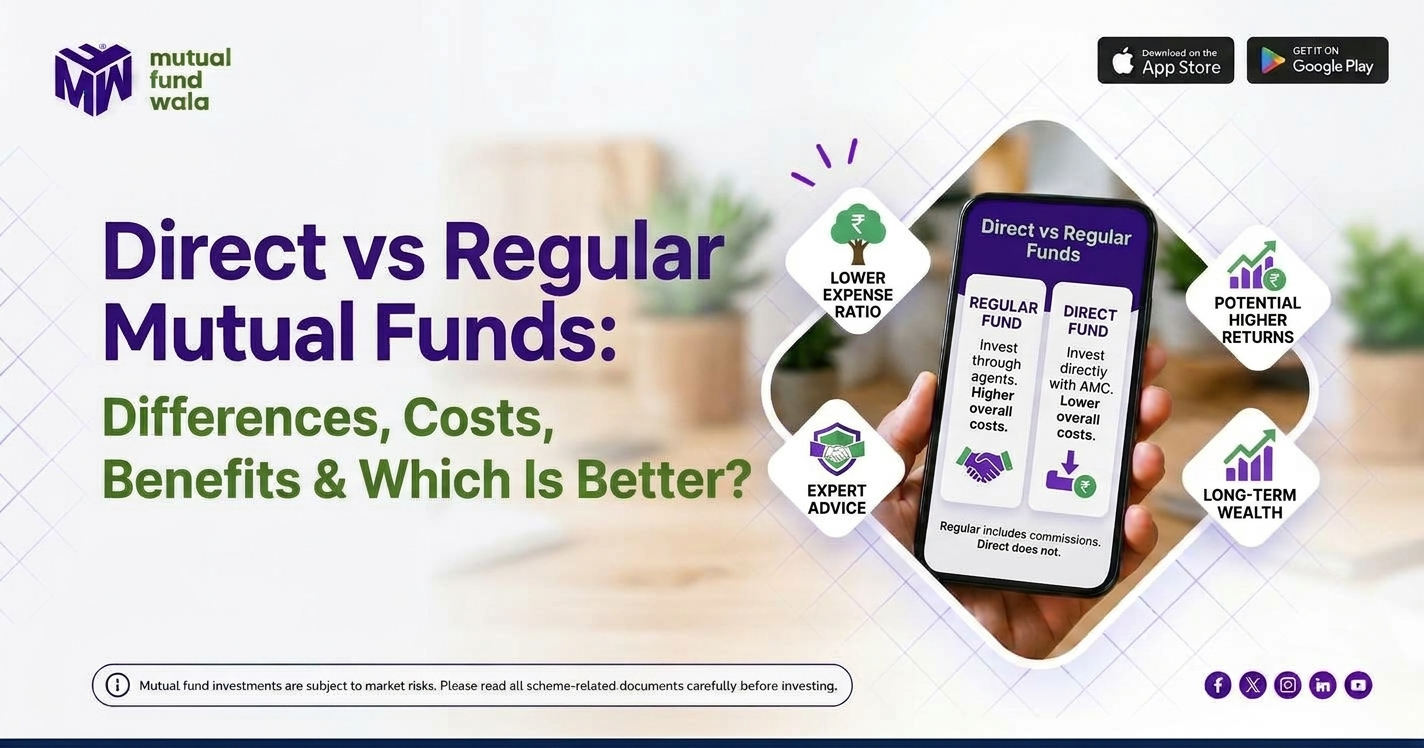
If you are comparing direct vs regular mutual funds, the core difference is simple: both plans invest in the same mutual fund scheme with the same fund manager, but you access them differently. The key difference lies in the distribution cost.
The main difference is the distribution cost. A Direct Plan does not involve a mutual fund distributor, while a Regular Plan is bought through a distributor. This difference is reflected in the mutual fund expense ratio and can affect your investment’s value over time.
Therefore, understanding direct vs. regular mutual funds matters before you invest. The choice is not only about costs and returns. It also depends on whether you prefer to manage your investments yourself or want professional assistance.
What Are Direct and Regular Mutual Funds?
Direct vs Regular mutual funds are two plans of the same mutual fund scheme. The portfolio and fund manager are the same, but the expense ratio is different because Regular Plans include distribution costs. Suppose a mutual fund offers an equity scheme in both Direct and Regular Plans.
Both plans invest in the same stocks and follow the same investment strategy. So, you are not choosing between two different portfolios. The difference comes from how you invest. In a Direct Plan, you invest without going through a mutual fund distributor or agent. Therefore, no distributor commission is paid or charged under the Direct Plan. . This results in a lower expense ratio.
In a Regular Plan, you invest through a distributor or intermediary. The AMC pays the distributor a trail commission for the investments brought through Regular Plans. This distribution cost is reflected in the plan’s expenses. Let’s summarise the difference between direct and regular mutual funds using this table:-
Direct Plan vs Regular Plan: Key Differences
| Parameter | Direct Plan | Regular Plan |
|---|---|---|
| Distributor Involved | No | Yes |
| Portfolio | Same | Same |
| Fund Manager | Same | Same |
| Expense Ratio | Lower | Higher |
| Distribution Commission | Not charged | Paid by AMC from scheme expenses |
| NAV | Usually higher over time | Usually lower over time |
| Investment Decisions | Investors make them independently | Distributor can assist |
| Suitable For | Investors comfortable researching funds | Investors who prefer distributor support |
The biggest difference between a Direct Plan and a Regular Plan is distributor involvement and the resulting difference in expense ratio.
Expense Ratio and Cost Difference
The main cost difference between Direct vs Regular mutual fund plans comes from distribution expenses. Direct Plans have a lower expense ratio because they exclude distributor commissions, while Regular Plans include distribution costs.
The mutual fund expense ratio is the cost the fund charges to manage and operate the scheme. It covers expenses such as investment management, administration, registrar services and other permitted costs. SEBI prescribes the maximum expense ratio limits under Regulation 52 of the SEBI Mutual Funds Regulations. The expense ratio is deducted from the scheme’s assets under management and therefore affects the Net Asset Value.
Even a small difference can matter over time. Suppose you invest ₹5 lakh in a mutual fund. The Direct Plan has an expense ratio that is 0.5% lower than the Regular Plan. Assume the fund earns 10% before expenses.
The direct vs. regular mutual fund returns could look like this:
| Parameter | Direct Plan | Regular Plan |
|---|---|---|
| Gross Return | 10% | 10% |
| Illustrative Expense Ratio | 1.0% | 1.5% |
| Approximate Return After Expenses | 9.0% | 8.5% |
| Investment Duration | 20 years | 20 years |
| Investment Amount | ₹5 lakh | ₹5 lakh |
| Final Corpus | ₹28.1 lakh | ₹25.6 lakh |
This is only an illustration. Actual expense ratios vary across schemes and can change over time. The important point is what happens to the difference when it compounds.
Suppose ₹5 lakh grows for 20 years at 9% a year. It would become roughly ₹28.1 lakh. At 8.5% a year, it would become roughly ₹25.6 lakh. That is a difference of about ₹2.5 lakh, even though the annual gap in returns was only 0.5%.
That is why you shouldn’t compare direct vs. regular mutual fund returns based on a single year. The effect of a lower expense ratio can become more noticeable over longer periods.
Are Direct Plans Always Better?
Neither direct nor regular plans are inherently better. This dilemma arises because many first-time investors focus only on cost and ignore other factors. A Direct Plan is cheaper, but you are responsible for making your own investment decisions.
If you have the knowledge to select funds, allocate assets, and track performance, you may `prefer to invest through direct plans. If you are not comfortable selecting and managing mutual fund investments on your own, a regular plan may be more suitable.
Regular plans cost more, but a distributor can help with fund selection, paperwork, transactions, and other investor services. Overall, the lower cost of a Direct Plan matters only if you can make sensible investment decisions on your own.
Benefits of Direct and Regular Plans
The first benefit is a lower expense ratio. Since there is no distributor commission, more of the scheme’s returns remain with the investor. The second benefit is the potential impact of compounding. A small annual cost difference (as shown in the above example) can become meaningful over a long investment horizon.
On the other hand, the main benefit of Regular Mutual Funds is guidance. A new investor may not know whether to choose a large-cap, mid-cap, hybrid or debt fund. A distributor can help select a suitable mutual fund scheme based on the investor’s goals and risk profile, and provide ongoing support with transactions and portfolio-related questions. This service has a cost, which is reflected in the higher expense ratio of the Regular Plan.
Direct vs Regular: Which One May Suit You?
Direct Plans may suit investors who can research mutual funds, understand risk and manage their investments independently. Regular Plans may suit investors who prefer guidance and are willing to bear the additional distribution cost for that service.
Consider two investors.
Investor A: Comfortable doing research
Riya understands mutual fund categories, compares expense ratios and reviews her portfolio once or twice a year. She knows why she selected each fund and doesn’t need help with basic transactions. A Direct Plan may make more sense for her.
Investor B: New to mutual funds
Aman is investing for the first time. He is unsure how to divide his money between equity and debt and does not know how to compare and select suitable funds. For him, a Regular Plan could be more suitable, particularly if the distributor provides useful guidance and ongoing support.
Thus, the choice depends on whether the additional service in a Regular Plan is useful to you. If you feel you need professional guidance to select and manage your mutual fund investments, a Regular Plan may be more suitable. Learn more about how to find a good mutual fund distributor.
Can You Switch From Regular to Direct?
Yes, you can generally switch from a Regular Plan to a Direct Plan of the same scheme, but the switch can have tax and other consequences. Before switching, investors should check the tax treatment.
A switch-out is generally treated as a redemption from one plan and the switch-in as a purchase. You can initiate switches through your fund house or through registrars like CAMS and KFintech. Thus, switching between Regular and Direct Plans can trigger capital gains tax because the existing units are effectively sold and new units are acquired. For this reason, you should calculate the tax impact on gains before moving from Regular to Direct.
Conclusion
The choice between Direct and Regular Plans ultimately depends on whether you are comfortable managing your mutual fund investments yourself or prefer the guidance and support of a distributor.
A Direct Plan can help reduce costs and may leave you with higher returns over a long period because of its lower expense ratio. A Regular Plan, on the other hand, gives you access to distributor support and guidance, but that service comes with an additional cost.
If you can research funds and manage a portfolio independently, the Direct Plan may be a sensible option. For someone who wants help with fund selection and investing, the Regular Plan can still have a place. The important thing is to understand what you are paying for. A lower expense ratio matters, but a well-managed investment process matters too.
FAQs
What is the difference between Direct vs Regular Mutual Funds?
The main difference is distribution. Direct Plans are bought without a distributor and have a lower expense ratio. Regular Plans involve a distributor and therefore include distribution costs. Both plans have the same portfolio and fund manager.
Do Direct vs Regular Plans have the same portfolio?
Yes. Direct and Regular Plans are part of the same mutual fund scheme and have the same underlying portfolio and fund manager
Why do Direct Plans have higher NAV?
Direct Plans have lower expenses. Over time, this means more of the scheme’s returns remain invested, which can result in a higher NAV than the Regular Plan of the same scheme.
Which gives higher returns, Direct or Regular Mutual Funds?
The portfolio performance is the same before expenses, but Direct Plans generally have a lower expense ratio. Therefore, their returns after expenses are generally higher over time, all else being equal.
Can I switch from Regular to Direct Mutual Funds?
Yes, you can generally switch within the same scheme. However, the switch is treated as a redemption of the existing Regular Plan units and a fresh purchase of Direct Plan units. This can result in capital gains tax.
Is a Regular Plan a bad choice?
No. A Regular Plan costs more, but that cost covers distribution and support. If you value guidance and assistance, the extra cost may be reasonable.