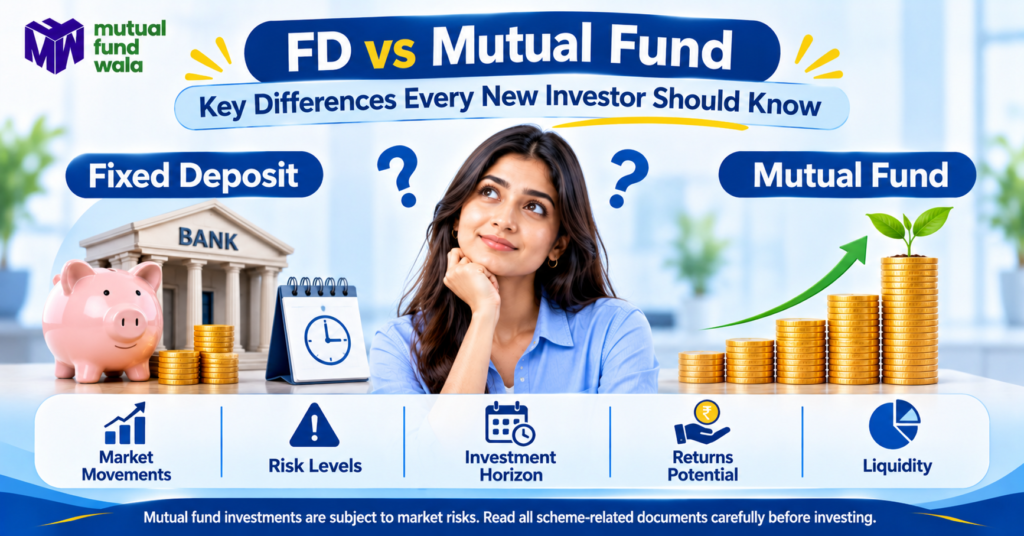
For many Indian households, a Fixed Deposit (FD) is the first investment that comes to mind when there is money to save. The reason is straightforward. You know the interest rate when you invest, the tenure is defined, and you can estimate the maturity amount in advance.
Mutual funds work differently. They invest in market-linked instruments such as shares, bonds, and money market securities. Their returns depend on the performance of the underlying investments and can fluctuate over time. This is where the FD vs mutual fund comparison becomes important.
Both investment options serve different financial needs. While FDs offer predictable interest income, mutual funds provide exposure to financial markets and the potential for long-term capital appreciation. Understanding returns, risk, liquidity, taxation and investment horizon can help you decide where to put your savings.
What Is a Fixed Deposit and What Is a Mutual Fund?
A Fixed Deposit (FD) is a deposit account offered by banks and other deposit-taking financial institutions. You invest a lump sum for a predetermined period at a fixed interest rate. The bank pays you interest on the deposit periodically. Depending on the FD type, the bank may also offer the option to reinvest the interest, adding it to the principal until maturity.
A mutual fund pools money from multiple investors and invests it in multiple securities and asset classes, such as equity shares, government securities, corporate bonds and money market instruments. A fund manager manages the portfolio according to the scheme’s investment objective. Unlike FDs, mutual fund returns are market-linked and are not guaranteed.
Key Differences Between FD and Mutual Fund
The difference between a fixed deposit vs mutual fund extends beyond the returns they generate. Risk levels, liquidity, taxation and investment requirements also vary.
| Parameters | Fixed Deposit (FD) | Mutual Funds |
|---|---|---|
| Returns | Fixed interest rate for the selected tenure | Market-linked returns that fluctuate |
| Risk | Relatively low, subject to the bank's creditworthiness and applicable deposit insurance | Depends on the underlying assets. Equity funds carry higher market risk than most debt funds |
| Capital Protection | Principal and contracted interest are payable subject to the bank's terms and creditworthiness | No guaranteed capital protection |
| Liquidity | Premature withdrawal may attract a penalty or reduced interest | Open-ended funds generally allow redemption on business days. An exit load may apply if sold within a short time. |
| Lock-in Period | Depends on the FD type. Tax-saving FDs have a five-year lock-in | Most open-ended funds have no lock-in, except schemes such as ELSS (3-year lock-in) |
| Minimum Investment | Varies by bank and deposit type | Varies by scheme and investment platform. Starts from ₹100 and ₹500. |
| Tax Treatment | Interest is generally taxed at your applicable income-tax slab rate | Depends on the fund category, acquisition date, and holding period |
| Inflation Protection | Fixed interest may not keep pace with inflation | Equity funds have the potential to outpace inflation over longer periods, but returns are not assured |
| Investment Management | No active portfolio management required | Managed by a fund manager, except certain passive funds that track an index |
The key difference between FD vs mutual fund is that an FD offers a predetermined interest rate, whereas mutual fund returns depend on market performance. This also means the two options serve different purposes within a financial plan.
FD vs SIP: What Happens If You Invest ₹10,000 Every Month for 10 Years?
A comparison becomes more meaningful when you look at how the investments could grow over time. Suppose you have ₹10,000 available every month and want to invest it for the next 10 years. You can put this money into a bank FD or invest it in a mutual fund through a Systematic Investment Plan (SIP).
For this illustration, we assume a monthly investment of ₹10,000 in both options over 10 years. This brings the total investment in each option to ₹12 lakh over the 10-year period. The FD earns a return of 6.6% and assumed mutual fund return is 12% and 10%. Mutual fund returns are illustrative and not guaranteed.
| Investment option | Monthly Investment | Annual Return | Final Value | Gain |
|---|---|---|---|---|
| Bank FD | ₹10,000 | 6.6% | ₹16.76 lakh | ₹4.76 lakh |
| Mutual Fund SIP | ₹10,000 | 12.0% | ₹23.23 lakh | ₹11.23 lakh |
| Mutual Fund SIP | ₹10,000 | 10.0% | ₹20.66 lakh | ₹8.66 lakh |
Note: FD calculation assumes annual compounding. Mutual fund calculations assume annualised returns and are illustrative, not guaranteed.
The difference becomes visible over a longer investment period. At an assumed 12% return, the mutual fund corpus is approximately ₹6.47 lakh higher than the FD value. The difference is ₹3.9 lakh at an assumed interest rate of 10%. However, the interest rate on an FD depends on the deposit tenure.
Compared to long-term FDs, the interest rate on short-term FDs may be lower. Mutual fund returns can be volatile and vary from year to year. An equity mutual fund may deliver returns above or below the assumed rate and can also generate losses.
What about post-tax returns?
Interest earned on an FD is added to taxable income and taxed at your applicable income-tax slab rate. This heavily reduces the compounding effect. Equity mutual funds, however, are taxed only when you redeem the units, and benefit from a lower Long-Term Capital Gains (LTCG) tax rate of 12.5% on gains exceeding ₹1.25 lakh.
For example, consider an investor in the 20% or 30% tax bracket.
| Investment Option | Taxable Gain | Post-Tax Corpus at 20% Slab | Post-tax corpus at 30% slab |
|---|---|---|---|
| Bank FD at 6.6% | ₹16.76 lakh | ₹15.8 lakh (at 5.28% effective annual return) | ₹15.3 lakh (at 4.62% effective annual return) |
| SIP at 12% | ₹23.23 lakh | ₹22.0 lakh | ₹22.0 lakh |
| SIP at 10% | ₹20.66 lakh | ₹19.7 lakh | ₹19.7 lakh |
Assumptions: FD interest is taxed annually at the applicable slab rate, excluding cess and surcharge. For the equity mutual fund, the entire investment qualifies for LTCG treatment. Equity mutual fund gains are taxed at the capital gains rates, not the investor's income-tax slab rate.
The comparison shows why taxation matters when evaluating investment returns. An FD offers predictable interest, while a mutual fund investor takes market risk for potentially higher returns. The higher assumed SIP corpus should not be interpreted as a guaranteed outcome.
You can use a SIP calculator to estimate how different monthly contributions and investment periods could affect your potential corpus.
FD vs Mutual Fund Returns: How Does Taxation Affect Your Earnings?
The FD vs mutual fund tax comparison decides how much you retain after redeeming an investment or receiving interest. FD interest is generally taxable at the applicable income-tax slab rate, irrespective of whether you withdraw the interest or reinvest it. Equity mutual funds follow a different capital gains tax structure based on the holding period.
Consider a ₹1 lakh investment to understand the difference. Assume an FD earns 6.60% interest over one year, while an equity mutual fund generates an illustrative 10% gain.
| Particulars | FD | Equity Mutual Fund |
|---|---|---|
| Initial Investment | ₹1,00,000 | ₹1,00,000 |
| Assumed Return | 6.6% | 10.0% |
| Pre-tax Gain | ₹6,600 | ₹10,000 |
| Tax at 20% Slab/ 20% Equity STCG Rate | ₹1,320 | ₹2,000 |
| Post-Tax Gain | ₹5,280 | ₹8,000 |
| Post-tax Value | ₹1,05,280 | ₹1,08,000 |
For an investor in the 30% income-tax bracket, the FD interest would attract ₹1,980 in tax, leaving ₹4,620 as post-tax interest. The equity mutual fund’s short-term capital gains tax would remain 20%.
If you hold equity mutual fund units for over 12 months, long-term capital gains are taxed at 12.5% on aggregate gains exceeding ₹1.25 lakh in a financial year. Accordingly, you will not have to pay any tax on the ₹10,000 capital gain, as it is below the ₹1.25 lakh exemption limit, assuming you have no other eligible LTCG in that financial year.
How are debt mutual funds taxed?
Debt mutual fund taxation depends on the scheme’s portfolio and the acquisition date. Gains from specified mutual funds acquired on or after 1 April 2023 are generally treated as short-term capital gains and taxed at the investor’s applicable slab rate, irrespective of the holding period.
Other categories may follow different tax rules. So do not assume every mutual fund offers the same tax advantage. Check the scheme category and applicable tax provisions before investing.
FD vs Liquid Fund: Where Should You Park Short-Term Savings?
If you want to park money for a few months or maintain an emergency reserve, comparing an FD vs a liquid fund matters. A liquid mutual fund invests primarily in short-term debt and money market instruments with maturities of up to 91 days.
A liquid fund lets you park surplus money while offering relatively stable returns. You can generally receive redemption proceeds within one business day, subject to applicable cut-off times.
An FD, on the other hand, offers a fixed interest rate for a chosen tenure. If you withdraw your money before maturity, the bank may charge a penalty. The main difference is that liquid funds are market-linked investments. They carry credit and liquidity risks, and their returns are not guaranteed.
You also pay tax on their gains as per taxation applicable for specified debt mutual funds. Choose an FD if you want a predictable maturity value. Consider a liquid fund if you need access to your money and are comfortable with some market risk.
FD vs ELSS: Which Is More Suitable for Tax Saving?
Both tax-saving fixed deposits and Equity Linked Savings Schemes (ELSS) qualify for deductions under Section 80C, subject to the overall ₹1.5 lakh limit. However, this deduction is available under the old tax regime, not the new tax regime.
| Particulars | Tax-Saving FD | ELSS |
|---|---|---|
| Lock-in Period | 5 years | 3 years |
| Returns | Fixed interest rate | Market-linked |
| Risk | Relatively low, subject to bank creditworthiness | Equity market risk |
| Tax Deduction | Eligible under Section 80C | Eligible under Section 80C |
| Tax on Returns | Interest is taxable at slab rate | LTCG above ₹1.25 lakh taxed at 12.5%, subject to conditions |
| Premature Withdrawal | Not permitted during the lock-in, subject to applicable rules | Not permitted during the lock-in |
The main difference is the risk and return structure. A tax-saving FD offers a predetermined and fixed interest rate, whereas ELSS invests primarily in equity and carries market risk. ELSS has a shorter lock-in period, but that does not make it suitable for every investor. Your choice should depend on your tax regime, investment horizon, and ability to tolerate value fluctuations.
When Is an FD the Right Choice?
An FD can be suitable when you prioritise predictable returns and capital preservation over market-linked growth. It may fit your financial requirements in the following situations:
- Short investment horizon: If you need the money within one to three years, an FD can provide a defined maturity amount.
- Low risk tolerance: If you are uncomfortable with fluctuations in investment value, an FD may offer greater predictability.
- Regular interest income: Investors who depend on interest payouts for household expenses may consider FDs with periodic interest payments.
- Emergency reserves: FDs can be part of an emergency fund, provided you account for premature withdrawal conditions and maintain sufficient accessible savings.
- Senior citizens: Bank FDs may suit retirees who prefer predictable interest income and want to avoid direct exposure to market volatility.
An FD is not necessarily an inferior investment simply because its return potential is lower than that of equity mutual funds. It serves a different role and suits investors with a low-risk profile.
When Are Mutual Funds a Better Fit?
Mutual funds may be more suitable when your investment objective involves long-term wealth creation and you can remain invested through market fluctuations.
Consider mutual funds when:
- You have a longer investment horizon: Equity mutual funds may be considered for goals that are at least five years away, depending on your risk tolerance.
- You want exposure to financial markets: Mutual funds allow you to participate in equity, debt, or a combination of asset classes without selecting individual securities.
- You can tolerate short-term volatility: Equity fund returns can fall during market corrections. You should be financially and emotionally prepared to stay invested through such periods.
- You want to invest regularly: SIPs let you contribute a fixed amount each month instead of committing a large sum at once.
- You are planning for long-term financial goals: Mutual funds can be part of a portfolio for goals such as retirement, children’s education or buying a house.
The key is to choose a mutual fund category that matches your investment horizon and risk capacity. Equity funds are not appropriate for every financial goal, especially when you need the money in the near term.
Conclusion
The FD vs mutual fund decision is not simply about choosing the investment that offers the higher return. It is about understanding what you expect your money to achieve and how much uncertainty you can accept along the way.
An FD can help you preserve capital and plan for expenses with a known maturity value. Mutual funds, particularly equity-oriented schemes, help build wealth over longer periods. But they require patience and the risk tolerance to withstand market volatility.
You do not necessarily have to choose one over the other. You can use FDs for short-term requirements and predictable income. At the same time, you can also allocate a portion of your long-term savings to mutual funds based on your financial goals and risk tolerance.
FAQs on FD vs Mutual Funds
Is a mutual fund safer than an FD?
No, a mutual fund is not safer than an FD. An FD generally offers a fixed interest rate for the selected tenure. Mutual funds carry market risk, and their value can rise or fall depending on the underlying investments and market conditions.
Can I lose money in mutual funds?
Yes, you can lose money in mutual funds. Equity mutual funds are exposed to stock market volatility, while debt funds face interest-rate, credit, and liquidity risks. Neither is risk-free.
What is the minimum investment in mutual funds vs FD?
The minimum investment amount varies by bank and mutual fund scheme. Some mutual fund schemes allow SIP investments starting at ₹100 or ₹500, while others require higher amounts. Banks also prescribe minimum deposit amounts for FDs, which are generally much higher than those for mutual funds.
Can I withdraw mutual funds anytime like an FD?
In most open-ended mutual funds, you can redeem your units on any given day. However, payments are processed only on business days. For funds like ELSS, which have a lock-in period, redemption is not permitted before that period expires. In the case of FDs, funds can be withdrawn prematurely, but this may attract a penalty.
Are FD returns guaranteed?
Banks offer a predetermined and fixed interest rate for the selected FD tenure. This makes the maturity amount predictable if you hold the deposit until maturity.