 Shashi Kant Bahl
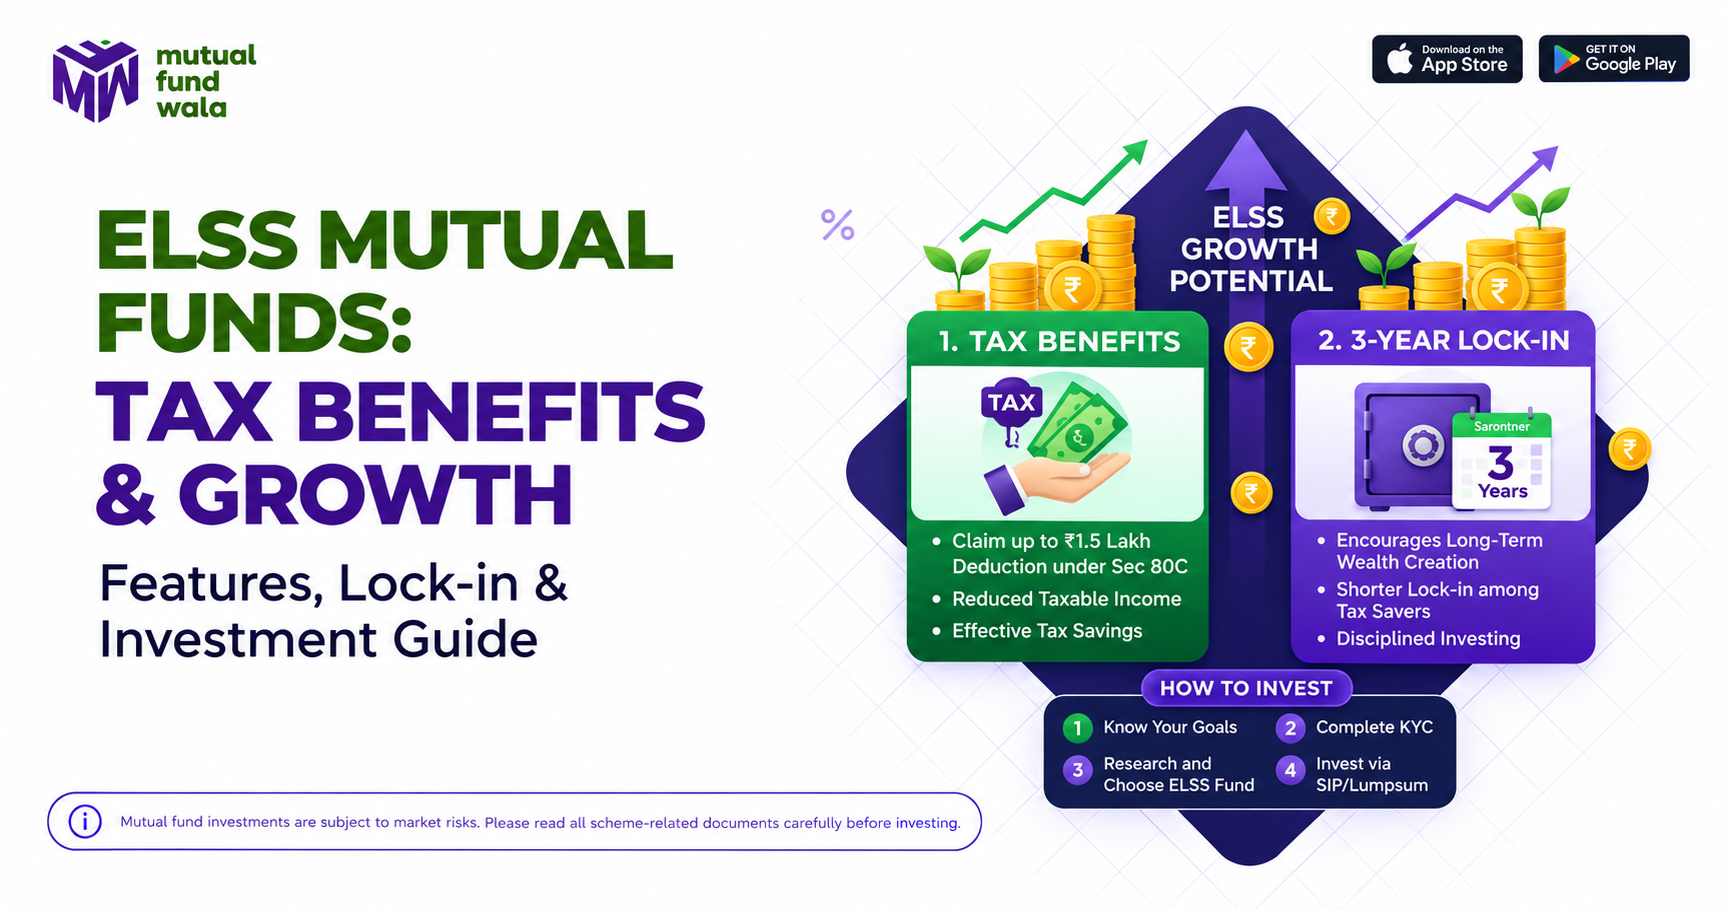
Saving tax is an important part of financial planning. However, choosing an investment solely for its tax benefits may not always help you achieve your long-term financial goals.
Equity Linked Savings Scheme (ELSS) mutual funds offer a way to combine tax-saving opportunities with equity investing. These funds invest predominantly in equities and provide tax deductions under Section 123 of the Income Tax Act, 2025, subject to the applicable tax regime.
Unlike traditional tax-saving instruments that offer fixed or government-backed returns, ELSS mutual fund returns depend on stock market performance. This means investors have the potential to earn higher returns over the long term, but they also face market-related risks.
Before investing, it is important to understand how ELSS mutual funds work, their lock-in period, tax benefits and suitability for different financial goals.
ELSS Mutual Funds Explained: What They Are & How They Work
ELSS mutual funds are equity-oriented mutual fund schemes that offer tax deductions under Section 123 of the Income Tax Act. These funds invest at least 80% of their assets in equities and equity-related instruments and have a mandatory three-year lock-in period. Their returns depend on the performance of the underlying investments.
ELSS funds pool money from investors and invest it across companies operating in different sectors. The fund manager selects stocks based on the scheme’s investment strategy and objectives. You can invest through a lump sum investment or a Systematic Investment Plan (SIP).
For example, suppose you invest ₹50,000 in an ELSS fund. The fund manager invests this money, along with contributions from other investors, in a portfolio of equities. As the market value of these investments changes, the fund’s Net Asset Value (NAV) also fluctuates. Your investment value rises or falls accordingly.
ELSS funds have three important characteristics:
- Equity exposure: At least 80% of the fund’s assets are invested in equities and equity-related instruments.
- Tax benefits: Eligible investments qualify for deductions under Section 123 in the old tax regime.
- Lock-in period: Every investment remains locked in for three years.
These characteristics make ELSS different from conventional tax-saving instruments such as the Public Provident Fund (PPF) and tax-saving fixed deposits.
Why Do ELSS Mutual Funds Have a 3-Year Lock-in?
ELSS mutual funds have a mandatory three-year lock-in because they are designed as tax-saving equity investment schemes. The lock-in prevents investors from redeeming their units before three years and encourages a longer investment horizon.
The lock-in period begins from the date of allotment of units. For example, if you invest ₹50,000 in an ELSS fund on 1 April 2026 and receive units that day, those units generally become eligible for redemption after completing three years. However, the lock-in works differently when investing through an SIP.
How does the ELSS lock-in period work for SIPs?
Each SIP instalment has its own three-year lock-in period. Suppose you invest ₹5,000 every month in an ELSS fund.
| SIP Instalment | Lock-in Completion |
|---|---|
| April 2026 | April 2029 |
| May 2026 | May 2029 |
| June 2026 | June 2029 |
| July 2026 | July 2029 |
The exact redemption eligibility depends on the allotment date of each instalment. Therefore, even if you stop your SIP after one year, you cannot redeem all the accumulated units together immediately after three years from the first investment. Post lock-in expiry, you can continue holding the units if they remain suitable for your financial goals.
ELSS Tax Benefits and Taxation
Eligible investors can access ELSS tax benefits under the old income tax regime. Investments qualify for a deduction of up to ₹1.5 lakh within the overall tax-saving limit of ₹1.5 lakh u/s 123. However, the deduction applies to the invested amount, while profits on redemption are subject to capital gains tax.
Tax deduction on ELSS investments
Consider an investor with an annual taxable income of ₹10 lakh who invests ₹1.5 lakh in ELSS.
| Particulars | Amount |
|---|---|
| Income Before Deduction | ₹10,00,000 |
| ELSS Investment | ₹1,50,000 |
| Eligible Deduction | ₹1,50,000 |
| Income After Deduction | ₹8,50,000 |
The illustration assumes the investor follows the old tax regime, has sufficient eligible income and has not exhausted the deduction limit through other investments.
Important: The ₹1.5 lakh limit is shared with other eligible investments and payments, including PPF and eligible life insurance premiums. ELSS does not provide an additional deduction above this limit. If you follow the new tax regime, you cannot claim the corresponding ELSS investment deduction.
Tax on ELSS mutual funds at redemption
Since ELSS units cannot be redeemed before completing three years, gains realised on redemption generally qualify as long-term capital gains (LTCG). In this case, LTCG exceeding ₹1.25 lakh in a tax year is taxable at 12.5%. The ₹1.25 lakh threshold is shared across eligible equity shares, equity-oriented mutual funds and other qualifying assets.
For example, suppose an investor redeems ELSS units and realises a gain of ₹2 lakh. Assuming there are no other relevant capital gains or losses:
| Particulars | Amount |
|---|---|
| Long-Term Capital Gains | ₹2,00,000 |
| Annual Exempt Threshold | ₹1,25,000 |
| Taxable Gains | ₹75,000 |
| Tax at 12.5% | ₹9,375 |
How Much Can You Invest in ELSS?
There is no statutory maximum investment limit for ELSS mutual funds. Investors can invest more than ₹1.5 lakh, but the tax deduction is restricted to the applicable overall limit. The minimum investment varies by scheme, You can start even lower with SIPs from ₹100 on the MutualFundWala app
For example, you may invest ₹2 lakh in an ELSS fund during a financial year. However, the maximum eligible deduction remains ₹1.5 lakh, assuming you have not already exhausted the limit. The remaining ₹50,000 does not qualify for an additional deduction, although it continues to participate in the fund’s investment performance.
ELSS Investment Example & Potential Returns
Consider an investor who makes a lump-sum ELSS investment of ₹1 lakh and holds it for five years. Assume the investment generates an illustrative annualised return of 10%.
| Particulars | Amount |
|---|---|
| Initial Investment | ₹1,00,000 |
| Investment Period | 5 Years |
| Assumed Annualised Return | 10% |
| Estimated Investment Value | ₹1,61,051 |
| Estimated Capital Gains | ₹61,051 |
In this illustration, the investment grows to approximately ₹1.61 lakh over five years. If the investor has no other eligible long-term capital gains during the relevant tax year, the ₹61,051 gain would fall within the ₹1.25 lakh annual threshold. However, actual ELSS mutual fund returns can differ substantially from the illustration.
Benefits and Risks of ELSS Mutual Funds
ELSS mutual funds combine tax-saving eligibility with equity investment opportunities. However, their suitability depends on an investor’s risk tolerance, investment horizon and financial requirements.
Benefits of ELSS mutual funds
- Tax-saving opportunity: Eligible investments can reduce taxable income under the old tax regime.
- Potential for long-term growth: Equity exposure provides an opportunity to participate in the growth of underlying businesses.
- Shorter mandatory lock-in: ELSS has a three-year lock-in, compared with five years for tax-saving fixed deposits.
- Flexible investment options: Investors can choose between lump sum investments and SIPs.
- Professional management: Fund managers select and manage investments according to the scheme’s objectives.
Risks of ELSS mutual funds
The principal risk is market volatility. Since ELSS funds invest predominantly in equities, their NAV can fluctuate with stock market movements. A three-year lock-in does not guarantee positive returns. If markets decline near the end of the lock-in, you may need to remain invested longer to avoid redeeming at an unfavourable value.
ELSS investments also carry liquidity risk because you cannot withdraw your money during the mandatory lock-in. Therefore, you should avoid allocating money to ELSS if you expect to need it within three years.
ELSS vs Other Tax-Saving Investments
| Parameter | ELSS | PPF | Tax-Saving FD |
|---|---|---|---|
| Investment Type | Equity mutual fund | Government-backed savings scheme | Bank deposit |
| Lock-in | 3 years | 15-year maturity | 5 years |
| Returns | Market-linked | Government-notified interest | Fixed bank interest |
| Investment Risk | Market risk | Sovereign-backed | Bank credit risk |
| Tax Deduction |
Old Regime: Eligible for deduction up to ₹1.5 lakh under Section 123. New Regime: No deduction. |
Old Regime: Eligible for deduction up to ₹1.5 lakh under Section 123. New Regime: No deduction. |
Old Regime: Eligible for deduction up to ₹1.5 lakh under Section 123. New Regime: No deduction. |
| Tax on Returns |
Old & New Regime: LTCG above ₹1.25 lakh in a financial year is taxable at 12.5%. |
Old & New Regime: PPF interest and eligible maturity proceeds are tax-free. |
Old & New Regime: Interest earned is taxable at the investor's applicable income-tax slab rate. |
PPF offers a government-backed savings option, while tax-saving fixed deposits provide greater predictability of returns. ELSS, meanwhile, provides equity exposure with the possibility of higher returns. However, ELSS also comes with greater market risk. The choice should depend on your financial goals, liquidity requirements and risk tolerance.
How to Invest in ELSS Mutual Funds
Investors can start an ELSS investment through a mutual fund house, registered intermediary or mutual fund investment platform. After completing the Know Your Customer (KYC) requirements, you need to select an ELSS scheme and choose between a lump sum investment and an SIP.
The following steps can help beginners get started:
- Identify your financial goal: Decide whether the investment is intended primarily for tax planning or longer-term wealth accumulation.
- Choose an ELSS scheme: Review its investment strategy, risk profile, expense ratio and performance across market cycles.
- Complete KYC: Provide the required identity and address details.
- Select the investment amount: Choose an amount that fits your budget and available tax deduction limit.
- Choose the investment mode: Invest through a lump sum or start an SIP.
- Review periodically: Monitor whether the scheme remains aligned with your financial goals.
Conclusion
ELSS mutual funds offer investors an opportunity to combine tax planning with long-term equity investing. Their three-year lock-in and eligibility for tax deductions make them distinct from conventional tax-saving investments. However, the tax benefit should not be the only consideration. Investors should evaluate their financial goals, risk tolerance and liquidity requirements before investing. Use our SIP calculator to estimate how monthly ELSS contributions could grow over time.
FAQs
What is an ELSS mutual fund?
An ELSS mutual fund is an equity-oriented tax-saving mutual fund with a mandatory three-year lock-in period. Eligible investments qualify for tax deductions under the old tax regime. Returns depend on equity market performance.
Can I withdraw ELSS after three years?
Yes, you can redeem your ELSS units after completing the mandatory three-year lock-in.
Is ELSS tax-free after three years?
No, completing the lock-in does not make the investment entirely tax-free. If gains exceed the applicable annual threshold (₹1.25 lakh for equity funds), they are subject to capital gains tax.
Can I claim ELSS tax benefits under the new tax regime?
No, the ELSS investment deduction is not available under the new tax regime.
Can I invest in ELSS through an SIP?
Yes, you can invest in ELSS through monthly SIPs. Each SIP has its own three-year lock-in period, calculated from the date of allotment.